If your business needs to send money abroad or make payments to accounts overseas, understanding the process can help make things simpler and more cost-effective.
Businesses send a large share of the world’s cross-border payments, and an efficient transfer method can lower what each one costs. How much can that add up if you make multiple international money transfers?
Top Reasons Why Businesses Send Money Abroad
Depending on their business models and operations, businesses may need to send money abroad for various reasons. Here are some of the most recurring reasons why businesses send money internationally:
Paying Suppliers in Different Countries
Many businesses source materials or products internationally, so they must transfer money to suppliers in other regions. In many cases, sending money internationally involves using currency conversions depending on the currency pairs involved.
For example, a clothing manufacturer might source fabric from an Italian supplier to ensure high-quality materials for its products.
Topping Up Overseas Business Bank Accounts
Companies often need to fund their overseas bank accounts to cover operational expenses in various locations. For instance, an international retail chain may need to top up accounts regularly in certain countries to manage local operational costs efficiently.
Managing Payroll for International Employees
Businesses with a global workforce must ensure timely payment to international employees. If payroll is done from a specific account, they could need to send money to specific accounts. An example would be a tech company paying developers based in India and the Philippines to maintain a global talent pool.
Making International Purchases
Purchasing equipment, inventory, or services from abroad requires international bank transfers. For example, a construction company buying specialized machinery from Germany must transfer money overseas to complete the purchase.
Running Operations in Multiple Countries
Managing day-to-day operations across multiple regions necessitates regular international fund transfers. For example, a global consulting firm might pay for office space and utilities in various countries, requiring frequent international money transfers.
Step-by-Step Guide to Sending Money Abroad
Are you preparing for your first overseas money transfer or looking for best practices for time and money on your next international money transfer? Here are some essential steps to consider to optimize your cross-border transfers:
1. Assess Your Needs
If your business frequently sends funds overseas, consider the nature and frequency of your transfers and respond to the following questions:
- Is the transfer amount involved consistent?
- Are these payments part of routine payments (such as payroll or supplier payments)?
- If you’re managing payments in multiple currencies, what currencies are involved?
Responding to these questions and monitoring this information over time will help you monitor your needs, whether you send or receive money from abroad.
Evaluate Exchange Pairs
When assessing your business’s needs for international money transfers, it is essential to understand the different exchange pairs you will be dealing with. Certain currency pairs have better liquidity and lower exchange rate markups, which can reduce your business’s costs.
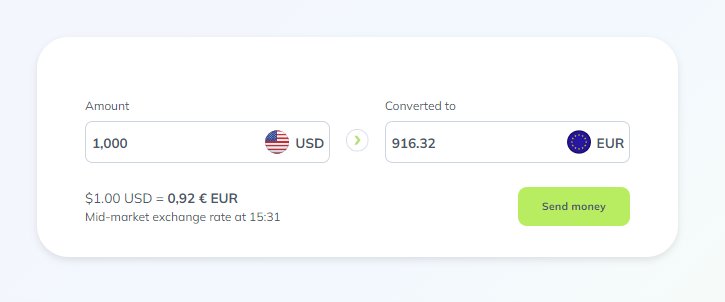
For instance, major currency pairs like USD/EUR or GBP/USD typically offer better rates than exotic currency pairs, which can have higher fees and lower availability.
Consider Fees
Fees associated with international money transfers can significantly impact your bottom line. These include upfront fees, hidden fees, and exchange rate markups. Businesses can evaluate the fees involved to choose the most cost-effective transfer method.
An exchange rate markup is an additional fee financial institutions add to the base exchange rate when converting currency, increasing the overall transaction cost.
For example, a business account with no FX markup on major currencies can help you avoid the hefty fees and exchange rate markups common with many banks and third-party money transfer services.
Urgency Matters
The urgency of your payments also plays a critical role in choosing the appropriate transfer method. If payments need to be processed quickly, options like wire transfers can ensure same-day or next-day delivery. However, faster transfers often come with higher costs.
Understanding the balance between speed and cost is crucial for managing cash flow efficiently and meeting business obligations without incurring unnecessary expenses.
One USD Balance: A Global Financial Tool
Keeping one USD balance and converting only when you pay can make regular cross-border transfers simpler and help you avoid repeated, costly currency conversions.
2. Choose a Payment Method and Methods for Sending Money Overseas
Selecting the right method for an international money transfer is crucial for managing costs, speed, and convenience. Depending on their specific needs, businesses can choose between traditional transfers, wire transfers, and third-party payment providers.
Traditional Transfers and Wire Transfers
Traditional and wire transfers are the most common ways to send money internationally. A traditional bank transfer is generally secure, reliable, and cost-effective, particularly for smaller or recurring payments. This type of transfer typically comes with low fees and processing times of 1-3 business days.
Wire transfers, in contrast, are best for high-value transactions due to their added security and predictability. They are frequently used when sending money overseas, especially for larger sums that require prompt delivery. However, due to the complexity of the transfer process, wire transfers can come with higher fees, but their reliability makes them a preferred choice for urgent, high-value transfers.
Transfers From One USD Balance
Paying from one USD balance is an efficient way to send money internationally.
You can pay in USD, or convert once and pay in your supplier’s currency, such as EUR or GBP. Local payouts help reduce costs and processing times.
Third-Party Payment Providers
Third-party payment providers and online platforms offer convenience but often come with higher fees and transfer limits. These are a convenient option for smaller, one-time payments. For example, a freelance graphic designer may use a third-party provider to receive payments from international clients, prioritizing convenience over cost.
3. Check the Exchange Rate
Monitoring the exchange rate is crucial because it directly impacts the amount your recipient will receive and your cost. Businesses should monitor trends, exchange rate markups, and market volatility before making international money transfers to maximize cost efficiency and reduce variable costs and fees related to unfavorable fluctuation.
Bancoli converts at the real interbank exchange rate, with free FX in 25+ currencies.
4. Decide on the Currency
Depending on your financial tools and services, when you transfer money, you can either pay in your business’s currency or convert it to the recipient’s currency before the transfer.
With Bancoli’s invoicing tool, you can create and send invoices and get paid into your USD balance. When you pay a supplier in another currency, Bancoli converts at the real interbank exchange rate. Similarly, paying directly in the destination currency helps avoid exchange rate uncertainty and can ensure a predictable amount for the recipient.
Before each payment, consider which currency works best for the transaction. Paying from one USD balance and converting only when you pay gives you more control over timing and exchange rate swings.
5. Preparing Recipient Information and Avoiding Transfer Errors
Accurate information is crucial when sending money abroad to avoid transfer errors. Before initiating a money transfer, make sure to collect all necessary details, including:
- Recipient’s name
- Bank account number or details for a wire transfer
- IBAN (International Bank Account Number)
- SWIFT/BIC code for international bank transfers
- Bank name
- Bank address (if required)
- Government-issued ID (if necessary for compliance)
Avoiding Transfer Errors
Accurate information helps ensure a smooth and error-free bank transfer, reducing the risk of delays or issues when sending money. Incorrect details can lead to complications, such as the transfer being delayed or the receiving bank being unable to process the payment.
Double-checking this information can prevent funds from going to the wrong recipient’s bank account or being delayed. Incorrect banking details or high transfer fees can cause a transfer to bounce back.
Many failed transfers come from incorrect or missing information. Common errors include incorrect IBAN or SWIFT codes, which can lead to delayed or failed transfers.
Set up and Make the Payment
Making a payment involves more than just clicking a button. Monitoring the money transfer, confirming that all steps are completed accurately, and tracking the payment’s progress is essential.
Bancoli sends notifications on the status of transfers to provide full visibility, ensuring a better customer experience for both parties.
6. Transfer Timelines
Transfers can take varying amounts of time depending on the destination country, currency pairs, banking hours, and other factors such as holidays or local regulations. Payments made in exotic currencies may have longer processing times compared to widely used currency pairs.
Impact of Currency Pairs on Transfer Timelines
Transfers involving major currencies like USD, EUR, and GBP typically take 1-2 business days, while transfers involving less commonly used currencies can take up to 7 days or more.
Transfers involving exotic currencies, such as the South African Rand (ZAR) or Indonesian Rupiah (IDR), can take up to 5-7 business days due to lower liquidity and additional fees for correspondent banks involved.
Time zones also play a crucial role in determining the transfer timelines. Transfers initiated late in the day may be delayed by different banking hours across countries, adding another day to the process. Understanding these timelines can help businesses plan cash flow effectively and avoid disruptions.
Sending Money with Bancoli: Efficiency and Convenience
With Bancoli’s Smart USD Wallet, you keep one USD balance and pay suppliers abroad through local payouts. When you pay in another currency, you get free FX in 25+ currencies. Bancoli is available in 150+ countries.
You can send USD to USD, or convert from your USD balance and pay in your supplier’s currency, such as EUR or GBP. Each payment converts once, which helps keep conversion costs down.
Bancoli also includes an invoicing tool. You can create, send and track invoices, and clients can pay you by ACH, RTP, US domestic wire or stablecoins. The money lands in your USD balance.
Bancoli uses multi-factor authentication and fraud monitoring to help keep your account safe. You control your funds. Bancoli does not own or control them. Smart USD is not a deposit and is not FDIC-insured.
In Conclusion
Sending money abroad might seem daunting, but it can be straightforward and efficient with the right steps. Start by assessing your business needs, choosing a reliable payment method, monitoring exchange rates, and double-checking recipient details.
Using a business account like Bancoli’s Smart USD Wallet can cut costs and simplify the process, making cross-border transactions smoother and more predictable. It’s all about having the right tools to give your business more control over international payments and cash flow.
Ready to see how it works? Take a look at the Smart USD Wallet.