A bank account transfer is the backbone of modern finance. This electronic movement of funds between financial institutions determines whether businesses meet payment deadlines and whether global transactions clear quickly. For both business owners and consumers, mastering these transfers is essential. It is crucial to manage cash flow effectively, avoid unnecessary fees, and ensure timely payments.
While the term “bank transfer” is often used generically, it actually encompasses several distinct methods. Each method has its own speed, cost, and risk profile. Choosing the right method is the difference between an immediate settlement and a multi-day wait.
In this comprehensive guide, we define the core types of electronic transfers. We correct common misconceptions about speed and cost, outline the regulatory landscape that governs transactions, and explain how leveraging modern platforms can transform your global financial operations into a cost-effective, streamlined process.
What is a Bank Account Transfer? Defining Electronic Fund Movement (EFT)
A bank account transfer is a broad term for Electronic Funds Transfer (EFT). EFT is the electronic exchange of money from one bank account to another, bypassing physical cash or paper checks. The core purpose is simple: process transactions quickly and securely.
Bank account transfers are the lifeblood of operations for business owners. They use them to:
- Transfer funds directly from sales proceeds into a business bank account.
- Pay employees via direct deposit (payroll).
- Settle invoices with vendors and suppliers (B2B payments).
- Transfer money between internal company accounts.
- Process customer refunds and expense reimbursements.
Crucially, the reliability, security, and speed of these transactions establish EFT as the preferred choice for modern commerce, surpassing traditional paper methods.
The Core Mechanics: ACH vs. Wire Transfer vs. Real Time Payments
Achieving maximum financial efficiency requires distinguishing between the three primary electronic transfer mechanisms. Simply, the network used dictates the payment’s speed, cost, and finality.
Here is a comparison of the key transfer types:
- ACH Transfer (Standard EFT)
- Network Used: Automated Clearing House (ACH)
- Speed & Settlement: 1 to 3 business days (Batch Processing)
- Cost to Sender: Free to low cost
- Ideal Use Case: Payroll, bill payments, recurring expenses
- Wire Transfer
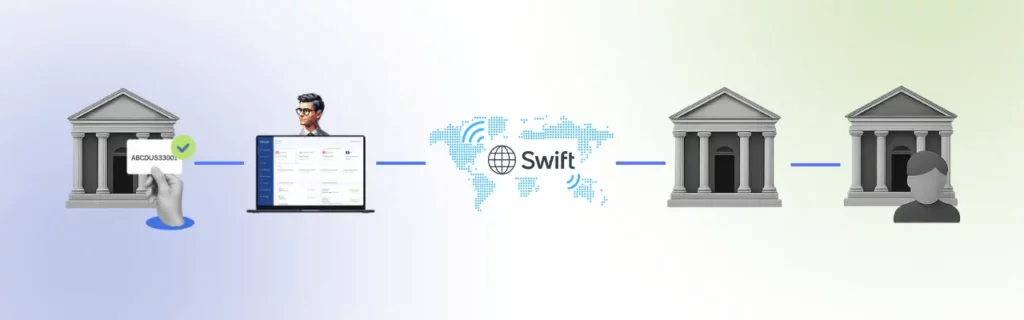
- Network Used: Fedwire (Domestic), SWIFT (International)
- Speed & Settlement: Same day (hours) to 1 to 2 days
- Cost to Sender: High (includes flat fee, intermediary charges, and currency markups)
- Ideal Use Case: High-value, urgent, and irreversible transactions
- Real-Time (RTP) Transfer
- Network Used: Real Time Payments (RTP) and FedNow
- Speed & Settlement: Arrives in minutes
- Cost to Sender: Varies (often low, sometimes flat fee)
- Ideal Use Case: Peer-to-peer, immediate consumer, or bill payment
1. ACH Transfers (Automated Clearing House)
ACH transfers are the most common “bank transfer” used for routine domestic transactions in the U.S. The Automated Clearing House network reliably processes these transactions in large batches several times daily.
They are ideal for routine and recurring payments where cost effectiveness and predictability are critical, such as direct deposit payroll, subscription payments, and online bill pay. With Bancoli, businesses get named USD account details on every plan, so they can receive ACH payments and send ACH transfers for their US operations.
Cost and Reliability
ACH transfers are highly cost-effective and highly reliable for routine payments. They initiate immediately, and while settlement (when the recipient accesses the funds) typically occurs within 1 to 3 business days, this process offers a low-fee structure ideal for frequent use. Users can also access expedited, same-day ACH service for a slightly higher fee when urgency is required.
2. Wire Transfers
Wire transfers move funds individually and immediately between financial institutions. They use global networks like Fedwire (domestic) and SWIFT (international).
Wire transfers are the preferred option for time-sensitive, high-value transactions that require immediate and irreversible settlement. These include real estate closing costs, large business acquisitions, and critical cross-border vendor payments where speed and certainty are essential.
Speed, Finality, and Global Benefit
Wire transfers are the fastest traditional payment method, with domestic wires often clearing and settling within minutes or a few hours, provided they are sent before the bank’s cutoff time.
A key benefit is the payment’s finality. Once received, funds are settled and cannot be reversed, which gives both parties certainty. While traditional wires involve significant costs, Bancoli customers get free FX in 25+ currencies when they send international payouts.
3. Real Time Payments (RTP)
Newer systems, such as the Real Time Payment (RTP) network and FedNow in the U.S., let payments arrive in minutes. RTP is well-suited for immediate consumer payments, urgent bill payments, and peer-to-peer transfers.
This truly represents the modern evolution of the bank account transfer. Bancoli has a fast option too. Transfers between Bancoli accounts are included on every plan.
Cost and Speed
RTP combines the speed of a wire transfer with the lower cost typical of other electronic fund transfers (EFTs). Payments arrive in minutes, and they are final. This helps with time-sensitive payments.
Why Bank Transfers Drive Operational Efficiency
Businesses of all sizes in different industries operate in a fast-paced global economy. Therefore, relying on streamlined bank transfers is a strategic imperative. This directly impacts profitability and operational efficiency.
Enhanced Cash Flow and Liquidity Management
Traditional paper checks create float time, the delay between payment issuance and funds clearance. Electronic bank transfers, especially same-day ACH and real-time payments, virtually eliminate this delay.
Improved Liquidity
Faster collection of customer payments via electronic means directly translates to better liquidity. This is beneficial because it allows your business to cover operating costs, invest in inventory, or seize growth opportunities. You can do this without waiting days for funds to settle.
Accelerated Collections
Modern invoicing tools integrate payment methods into the invoice and support bank transfers. Additionally, some invoicing tools allow sellers to offer incentives for early payments, further enhancing cash flow and improving the working capital cycle.
Streamlining B2B and Payroll Operations
The reliability and predictability of scheduled bank transfers are crucial. They help maintain strong business relationships and boost internal efficiency.
- Reliable Supplier Payments: Setting up recurring ACH transfers ensures timely, reliable payments to suppliers. This stability builds trust. Besides, it secures better payment terms and can qualify your business for early payment discounts.
- Efficient Payroll: Direct deposit via ACH is the standard for payroll processing. It automates the complex, critical task of paying employees accurately and reliably. This automation reduces administrative overhead and eliminates the costs associated with printing and distributing physical checks.
- Transaction Versatility: Bank transfers can handle virtually any type of transaction, from customer refunds and expense reimbursements to large-scale vendor payments, all with clear audit trails.
Global Banking Decoded: Local vs. International Bank Transfers
Efficient cross-border finance requires understanding the transfer mechanisms used in different regions.
Domestic Transfers
Local transfers are simple and fast. They rely on the country’s established domestic clearing networks:
- United States: Automated Clearing House (ACH), Fedwire, Real Time Payments (RTP), and FedNow.
- United Kingdom: BACS (slower) and Faster Payments (usually seconds).
- Eurozone: Single Euro Payments Area (SEPA), including SEPA Instant Credit Transfer.
Because these payments use local infrastructure, they are typically faster and cheaper, often settling within minutes or hours.
International Transfers: Global Reach via the SWIFT Network
Historically, international bank account transfers relied almost exclusively on the SWIFT (Society for Worldwide Interbank Financial Telecommunication) network. SWIFT is the global messaging system that facilitates international wire transfers.
The primary strengths of the SWIFT network include:
- Maximum Global Coverage: SWIFT is the most established and universally accepted system for institutional transfers, ensuring connectivity between virtually every bank globally.
- Certainty and Finality: Payments sent via SWIFT are highly final, offering security and assurance to the recipient upon successful receipt of funds.
The cost structure of a traditional SWIFT transfer is characterized by multiple components:
- Outgoing Fee: The sending bank usually charges a flat fee to send the wire.
- Intermediary Fees: Correspondent banks may deduct their own fees as payments are routed internationally. This impacts the final amount received and introduces variability.
- Currency Conversion Costs (FX Margin): This is the bank’s Foreign Exchange (FX) fee. Traditional banks apply an exchange rate that includes a hidden margin, resulting in a hidden fee on the principal amount. When dealing with exotic currency pairs, correspondent banks may perform multiple conversions along the SWIFT route, resulting in several compounded FX fees being deducted.
A Modern Solution: Local Payment Rails and Named USD Account Details
Modern platforms help businesses avoid the slow, layered SWIFT system. Some other providers offer multi-currency business bank accounts. Bancoli keeps it simpler: you get paid in USD and pay others on local rails.
With Bancoli, US clients pay you by ACH, RTP or US domestic wire to your named USD account details, available on every plan. When you pay suppliers abroad, Bancoli can send local payouts, for example in euros, with free FX in 25+ currencies.
Each payment is treated as a local payment in the country where it lands. That avoids international wire fees, and funds often arrive the same day instead of after a multi-day SWIFT wait. It truly allows businesses to “pay like a local” and enables smoother global trade.
Managing Fees and Limits: What You Need to Know
Understanding the fee structure and transaction limitations is vital. It helps you optimize any bank account transfer strategy.
Deciphering Transfer Fees
Here is a breakdown of typical transfer fees:
- Sender Fee (Outgoing)
- ACH/Standard EFT: Free to low cost (often free for consumers)
- Wire Transfer (Domestic): Flat fee set by the sending bank
- Wire Transfer (International): Usually a higher flat fee set by the sending bank
- Recipient Fee (Incoming)
- ACH/Standard EFT: Usually US$0
- Wire Transfer (Domestic): Some recipient banks charge a fee
- Wire Transfer (International): Fee charged by the recipient bank, plus any intermediary fees
- Intermediary/Correspondent Bank Fee
- ACH/Standard EFT: Not applicable
- Wire Transfer (Domestic): Not applicable
- Wire Transfer (International): Varies (deducted along the way)
- Currency Conversion Cost (FX Margin)
- ACH/Standard EFT: Not applicable (usually domestic only)
- Wire Transfer (Domestic): Not applicable
- Wire Transfer (International): Hidden markup built into the exchange rate
Transaction Limits
Banks impose daily or monthly limits on electronic transfers. They do this to mitigate risk and comply with regulatory requirements.
- ACH Limits: Limits vary by bank and account type. For Same Day ACH, Nacha sets a cap of US$1 million per payment.
- Wire Transfer Limits: Wire transfers are designed for high-value transactions and generally have much higher limits than ACH. Limits vary widely by bank and account type, but they can reach US$1 million or more for established business accounts.
Always consult banking schedules and limits. These factors determine whether an ACH or a wire transfer is the most cost-effective solution for a specific payment.
You can always compare and choose from different payment methods depending on your transaction needs.
Regulatory Landscape: Compliance and Fund Security
Stringent global and local regulations maintain the security and integrity of bank transfers. For any business managing payments, compliance is non-negotiable.
Anti Money Laundering (AML) and KYC
Anti-Money Laundering (AML) laws mandate that financial institutions monitor transactions and create an audit trail to prevent illegal funds from entering the system.
Know Your Customer (KYC) is the essential due diligence process where banks verify client identities and financial activities.
While compliance checks can sometimes cause minor delays in large international transfers, these procedures are vital for protecting all parties against fraud and financial crime.
Protecting Your Transfers
Banks secure transactions using strong encryption, fraud detection tools, and multifactor authentication (MFA). However, user vigilance is the best defense against cyber threats. Follow these critical tips to avoid online banking scams:
- Verify the Sender’s Address: If an email requests financial details or urgent action, call the party directly using a trusted phone number (not one provided in the suspicious email) to verify legitimacy.
- Hover Over Links: Before clicking any link in an email, hover your cursor over it to reveal the true destination URL. If the address looks suspicious, do not click.
- Never Share Personal Details: Legitimate financial institutions will never ask for your password or security answers via an unsolicited email. Do not share credentials under any circumstances.
- Use Secure Connections: Always initiate bank account transfers and sensitive transactions using a secure, private internet connection. Avoid public Wi-Fi networks when handling financial data.
How to Execute a Bank Account Transfer: The Bancoli Method
Sending money with Bancoli is simple. Here is how it works.
Step 1: Sign In to Your Bancoli Account
Sign in to your Bancoli account and open your Smart USD Wallet. You control your funds. Bancoli does not own or control them.
Step 2: Selecting the Destination Account and Currency
Specify the destination account. For external transfers, accurately provide the verified recipient banking details: Recipient Name, Account Number, and the required bank codes (the routing number for US payments, or the local details the destination country uses, such as an IBAN for euro payments). Then, define the exact payment amount.
Step 3: Finalize and Confirm Completion
Review the complete transaction summary, ensuring all payment details are correct. Approve the transfer with MFA or a passkey. You then see a message confirming that your transfer is being processed.
Conclusion
A secure, swift, and cost-effective bank account transfer is the backbone of the modern global economy. Whether you are a solopreneur paying and getting paid across borders or a growing business processing payroll, understanding the distinction between ACH, wire and real-time payment methods is essential for financial health.
Bank transfers reduce the burden of cash handling fees, streamline B2B and payroll operations, and fortify trust in business transactions.
Frequently Asked Questions
What is the primary difference between a bank transfer and a wire transfer?
The terms are often confused, but they differ in speed, cost, and network. A bank transfer commonly refers to an ACH (Automated Clearing House) transfer. This transfer is low-cost or free, processed in batches, and settles in 1 to 3 business days. A wire transfer is high-cost (with a flat fee), processed individually, usually the same day, and is generally irreversible.
Are all bank account transfers fast?
No. Real-time payments, such as RTP and FedNow, usually arrive in minutes. Standard domestic bank transfers (ACH) take 1 to 3 business days because they are processed in batches.
How long do international bank transfers typically take?
Traditional international bank transfers using the SWIFT network typically take 1 to 5 business days. The time depends on the sending and receiving banks’ cut-off times, the number of intermediary banks involved, and necessary regulatory compliance checks. Bancoli sends local payouts, and payout timing depends on the local rail and route.
What information is required to make a bank account transfer?
For a standard domestic transfer, you usually need the recipient’s full name, their bank’s routing number (ABA number), and their bank account number. For international transfers, you will also need the recipient’s bank’s SWIFT/BIC code and, depending on the destination country, an IBAN (International Bank Account Number).
Can I reverse a bank account transfer if I send money to the wrong account?
It depends on the type. ACH transfers can often be reversed or recalled, especially if an error is reported quickly (within 5 business days). Wire transfers are designed to be immediate and are highly difficult, if not impossible, to reverse once the recipient bank accepts the funds. Always double-check wire details before finalizing the transaction.
Are international bank transfers expensive?
Yes, traditional international bank transfers (SWIFT wires) are expensive due to three factors: high flat fees charged by the sending bank, intermediary bank charges deducted en route, and significant hidden costs caused by unfavorable currency exchange rate markups (a hidden cost built into the rate). Modern platforms help cut these costs. Bancoli, for example, offers free FX in 25+ currencies.
Why do businesses prefer bank transfers over paper checks?
Businesses prefer electronic bank transfers because they offer superior speed, enhanced security (via encryption and authentication), elimination of cash-handling costs, and improved cash flow due to the immediate reduction in float time. They also create a clear, digital audit trail for accounting and compliance purposes.