Selecting the right cross-border payments for international businesses determines the speed and cost of your global trade operations. For most companies, the price of cross border payments remains an invisible tax, often draining 2-4% of every invoice through hidden FX markups.
If you rely on traditional wire transfers for every corridor, you are likely overpaying for speed you might not always need.
Modern treasury management requires a tiered approach to global money movement. By matching the specific corridor and urgency of a payment to the most efficient rail, businesses can protect their margins and improve cash flow predictability.
Key Takeaways
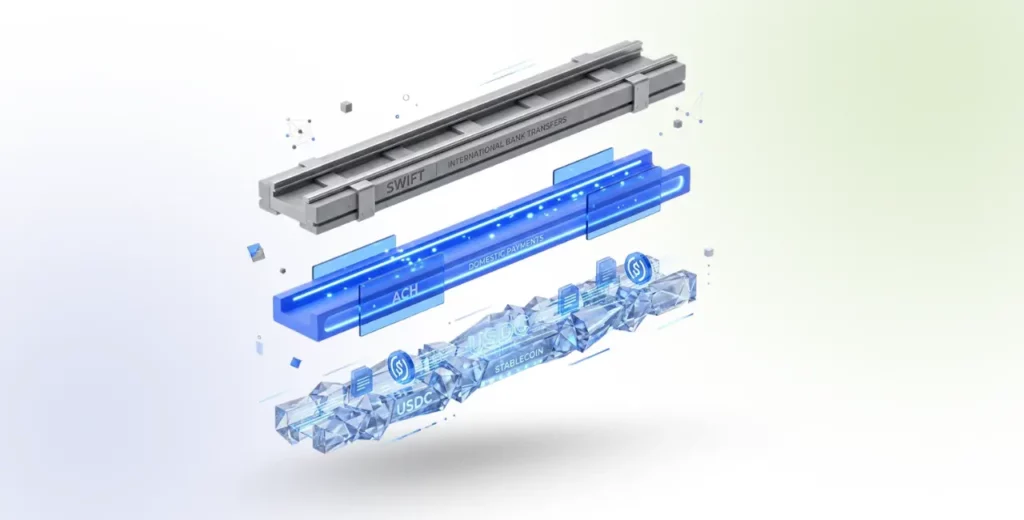
- Use local ACH rails for non-urgent vendor payments to reduce fees by up to 80%.
- Reserve SWIFT wire transfers for high-value, time-critical transactions only.
- Deploy stablecoin settlement (USDC) for cross-border liquidity in minutes.
- Unify international payments in one USD account with free FX in 25+ currencies to simplify reconciliation.
Legacy banking systems operate on a correspondent network that was designed decades ago. This framework results in “lifting fees” where intermediary banks take small cuts of your transfer without prior notice. Consequently, in 2026, international businesses are shifting toward unified payment infrastructure that provides direct access to local rails under the ISO 20022 standard.
Furthermore, unified platforms eliminate the “middle man” by using local bank details in multiple jurisdictions. This allows you to receive a payment in EUR as if you were a local European company. As a result, you can bypass the expensive international wire network entirely and protect your profit margins.
Comparing cross-border payments for international businesses
Choosing the correct method involves balancing three factors: cost, speed, and reliability. Modern treasury teams often use these methods in tandem with multi-currency cash forecasting to ensure they have the right liquidity in the right rails at the right time.
| Method | Settlement Speed | Cost Level | Bancoli Use Case |
|---|---|---|---|
| ACH | 1-3 Business Days | Low ($0 to $1) | Recurring vendor payroll |
| Wire (US domestic, Fedwire) | Same Day / 24h | High (bank fees vary) | Urgent supply chain bills |
| Stablecoin (USDC) | Minutes | Very Low (Gas fees) | Moving USD stablecoins between wallets |
| RTP (US) | Minutes | Moderate | Urgent US collections |
Why cross border payments failures happen
The transition to ISO 20022 standards means that data quality is now as important as the funds themselves. Banks are increasingly rejecting transfers with unstructured postal addresses or missing purpose codes. To ensure your cross-border payments for international businesses work reliably, you must use an infrastructure that validates receiver data before the funds leave your account.
Selecting the right cross-border payments for international businesses
Businesses must stop viewing global payments as a “one size fits all” process. A diversified payment stack allows you to optimize for different regions. For example, if you are paying a manufacturer in Mexico, using a local SPEI transfer is faster and cheaper than an international wire.
In addition, if you are collecting from a client in Brazil, utilizing the PIX network provides near-instant settlement. Similarly, if you are collecting from a client in the USA, providing them with local ACH details removes the friction that often delays settlements. Bancoli lets you get paid in the US by ACH, RTP, US domestic wire or stablecoins, and send local payouts, from a single interface.
Diagnostic: The “Lifting Fee” check
Answer these questions to see if your current methods are draining your revenue:
- Does your recipient often receive less than the amount you sent?
- Do you pay more than $15 for a standard international transfer?
- Is your FX markup currently above 1%?
- Do you lack visibility into the exact status of your payment while in transit?
- Does your bank charge you to receive international funds?
How Bancoli unifies cross border payments
Bancoli gives you named USD account details on every plan, including Free, once your account is verified, so US clients can pay you by ACH, RTP or US domestic wire. From the same account, you can send local payouts with free FX in 25+ currencies. This unified approach to cross-border payments for international businesses eliminates the traditional complexity of global cash management.
Our system automates the selection of the most efficient rail for every corridor. By eliminating hidden FX fees and providing transparent, interbank rates, Bancoli helps you scale your cross border payments strategy securely.
Conclusion
The best international payment methods are the ones that align with your business goals: speed for agility and local rails for margin protection. Diversifying your payment stack is the only way to remain competitive in a global market.
Frequently Asked Questions
What are the most common international payment methods?
The most common methods include SWIFT wire transfers, local ACH (USA), SEPA (Europe), and increasingly, stablecoin settlements like USDC. Each method has different trade-offs regarding cost and speed.
Which international payment method is the cheapest?
Local ACH and SEPA transfers are typically the cheapest, often costing less than $1 per transaction. However, they are usually slower than wires or stablecoins.
How long does an international payment take?
Wires typically take 24-48 hours. Local rails like ACH take 1-3 business days. Stablecoins and Real-Time Payment (RTP) networks settle in minutes or seconds.
What is a lifting fee in international banking?
A lifting fee is a charge taken by an intermediary bank while your money is in transit between your bank and the recipient’s bank. These fees are often hidden and reduce the final amount received.
How does Bancoli reduce international payment costs?
Bancoli gives you named USD account details for ACH, RTP and US domestic wire, plus local payouts with free FX in 25+ currencies, so you can skip the SWIFT network.