In the ever-evolving landscape of global finance, SEPA (Single Euro Payments Area) payments are emerging as a pivotal force, transforming how businesses manage their finances.
This innovative approach, adopted by many financial institutions, redefines the efficiency of cross-border payments. SEPA stands out as a streamlined platform, bridging the gap between the complexity of international transactions and the simplicity of domestic payments.
Gone are the days when businesses grappled with hefty currency conversion fees and convoluted cross-border payment options. SEPA payments empower businesses to easily transfer funds across borders akin to domestic electronic payments. This not only helps save money but also simplifies the financial processes.
This article delves into how SEPA is revolutionizing the financial world for businesses. We’ll explore the basic steps in making a SEPA payment and how businesses can leverage this platform to enhance their financial operations.
What is SEPA?
SEPA is an initiative of the European Union that standardizes payments to facilitate easier, faster, and more efficient transactions across European nations. This streamlined process encompasses various payment methods, including credit transfers, direct debits, and card payments.
The Single Euro Payments Area (SEPA) stands as a monumental development in the realm of European finance. It represents a unifying force, harmonizing how payments are processed across Europe. SEPA’s inception and evolution have significantly influenced how businesses and individuals handle financial transactions within countries and across European borders.
By simplifying and unifying payment methods, SEPA has effectively erased the financial borders within the EU, enabling businesses and consumers to make and receive payments under the same basic conditions, rights, and obligations, irrespective of their location.
How do SEPA transactions work?
SEPA works with transactions involving the euro, regardless of where the sender and receiver are located. While most SEPA member states are in Europe, some non-European countries also participate.
Here’s a breakdown:
Transactions supported by SEPA
- Within the SEPA zone: This includes all EU member states (except Denmark) and several non-EU countries like Iceland, Norway, Switzerland, and Liechtenstein. Transactions in euro between accounts in these countries are treated as domestic payments, regardless of the location.
- Between the SEPA zone and non-SEPA countries: Some non-SEPA countries have agreements with SEPA members, allowing euro payments to be processed through the SEPA network. However, these transactions might incur additional fees and take longer to process.
Transactions not supported by SEPA
- Non-euro transactions: SEPA only works with euro payments. If you make a payment in another currency, it will not be processed through the SEPA network.
- Transactions within non-SEPA countries: SEPA does not directly cover transactions within non-SEPA countries, even if they use the euro.
The Emergence of The Single Euro Payments Area: A New Banking Standard
The journey of SEPA began in the early 2000s, with the European Payments Council (EPC) playing a pivotal role. The fragmented nature of European financial systems, where each country had its own set of rules and standards for processing payments, posed significant challenges for cross-border trade and economic integration.
The EPC, in conjunction with the European Central Bank and the European Commission, initiated SEPA as a means to unify payment structures across the European Union (EU). This initiative was a response to the growing need for an efficient, cost-effective, and seamless payment system that could support the dynamic economic environment of the EU.
The Aim and Purpose of SEPA in the European Financial System
The primary aim of SEPA is to create a single market for euro payments within the EU. By doing so, it not only simplifies the payment process but also enhances the efficiency of border payments. SEPA’s role extends beyond mere transactional convenience. It’s an essential component in the broader objective of the EU to foster economic and financial integration among its member states.
The right payment methods, those that are quick, reliable, and uniform across countries, are crucial in achieving this goal. SEPA aligns with the EU’s vision of a barrier-free payment area, where consumers and businesses can make cashless payments across Europe as effortlessly as they would within their own countries.
The Role of the European Central Bank and European Commission
The European Central Bank (ECB) and the European Commission have been instrumental in elevating SEPA as a premier cross-border payments platform, significantly boosting cross-border payments efficiency.
Their collaborative efforts have streamlined the process of sending cross-border payments, making international money transfers more accessible and user-friendly. By fostering cooperation among European banks, they have facilitated various payment options, ensuring that money transfers occur smoothly within the SEPA framework.
This synergy has enabled businesses and individuals to transact in their own currency, enhancing trade across global markets. The ECB’s role extends beyond facilitation. It diligently oversees SEPA’s performance. It also ensures that this single platform consistently adheres to the high standards set by these regulatory bodies. Maintaining the integrity and efficiency of cross-border transactions within the SEPA system.
The Geographical Reach of SEPA
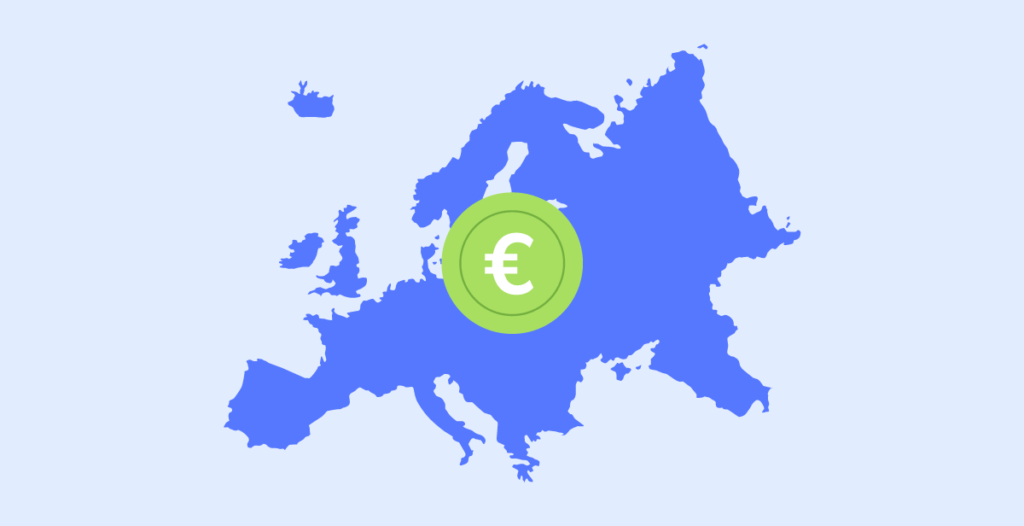
As of January 2022, SEPA has 36 member-states: Andorra, Austria, Belgium, Britain, Bulgaria, Cyprus, Croatia, Czech Republic, Denmark, Estonia, Finland, France, Germany, Greece, Hungary, Republic of Ireland, Italy, Latvia, Lithuania, Luxembourg, Malta, Monaco, Netherlands, Poland, Portugal, Romania, San Marino, Slovenia, Slovakia, Spain, Sweden, Switzerland, Vatican City & the 3 EEA countries of Norway, Liechtenstein, Iceland.
Advantages of SEPA Accounts for Businesses
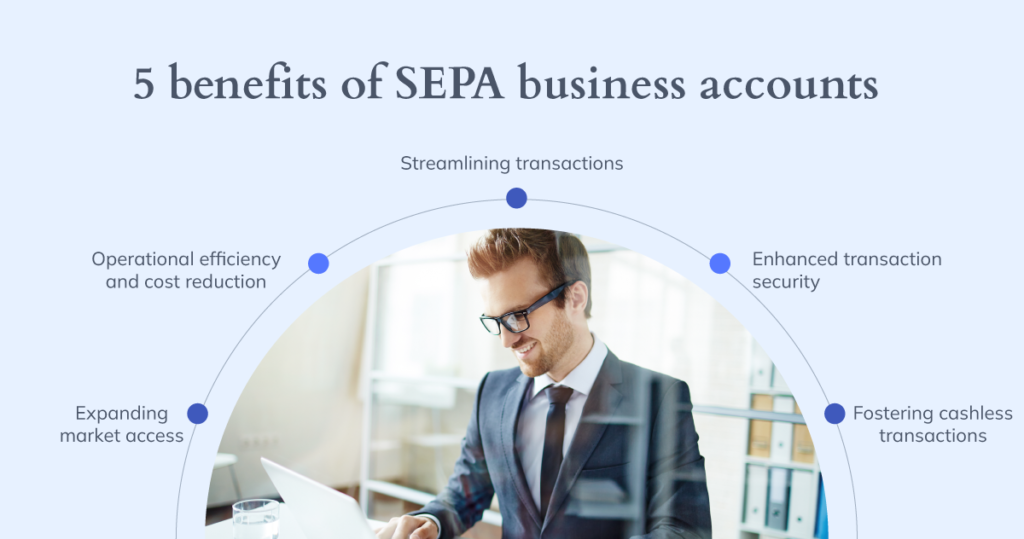
Implementing the Single Euro Payments Area (SEPA) accounts has revolutionized the dynamics of financial transactions for businesses across Europe.
The most notable aspect of the SEPA is the ability to make Global ACH payments. This payment method allows you to make cross-border payments on time without high transaction fees associated with international wire transfers. It also eliminates the hassle of using paper checks.
You can achieve optimal tracking with a payments platform that automates global ACH payments. This gives you a view of each payment, including payment status updates, invoice due dates, and failed payments.
Streamlining Transactions
SEPA has significantly enhanced the speed and efficiency of cross-border payments within the EU. By standardizing the payment methods, SEPA allows businesses to accept payments more swiftly than traditional methods. This streamlined approach eliminates the delays often experienced in international trade, particularly in wire transfers and dealing with varying exchange rates.
The harmonization of transactions means that businesses can expect the same level of efficiency in cross-border payments as they do with domestic and international payments now, ultimately improving the overall payment experience for both businesses and consumers.
Operational Efficiency and Cost Reduction
SEPA creates a single market for euro payments, boosting economic activity and cross-border trade. By unifying the payment methods across the EU, transaction fees are significantly reduced, especially when compared to the fees associated with traditional cross-border payment methods. This uniformity in transaction fees simplifies the payment process and helps businesses with better financial planning and management.
Consolidating multiple bank accounts into a single SEPA account reduces administrative burden and overheads. This allows businesses to focus more on growth and less on managing financial logistics.
Enhanced Transaction Security
Security remains a paramount concern in the payments industry. SEPA requires strong authentication and fraud prevention measures, offering better protection against financial crime. The standardized format and centralized infrastructure of SEPA facilitates monitoring and analysis of payment activity.
SEPA regulations provide robust consumer protection mechanisms, including dispute resolution procedures.
Fostering Cashless Transactions
SEPA plays a pivotal role in promoting digital payments across the European Union. SEPA customers can make cashless euro payments, via credit transfer and direct debit, to anywhere in the European Union, as well as a number of non-EU countries, in a fast, safe, and efficient way, just like national payments.
Expanding Market Access
One of the most significant impacts of SEPA is its role in expanding market access for businesses within the European Union. SEPA’s unified payment system breaks down the financial barriers that previously hindered international trade.
Thanks to standardized payment processes, businesses can now easily tap into new markets. This access to a broader market drives growth and fosters competition and innovation within the European business landscape.
Navigating SEPA Payments: A Step-by-Step Guide
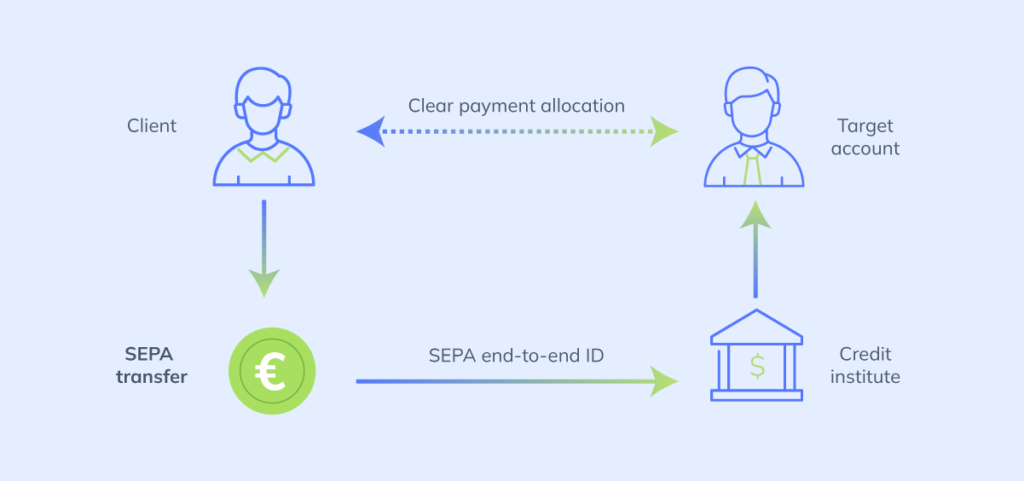
Every bank account in the SEPA area is assigned an International Bank Account Number (IBAN), the European equivalent of a US account number.
Like domestic bank transfers made using the ACH and Fedwire networks require both parties’ bank account and routing numbers to complete a funds transfer, SEPA transfers require the IBAN identification codes of all European accounts involved in the transaction.
Here’s an overview of how different types of SEPA transfers work:
SEPA Credit Transfer
SEPA Credit Transfers are one-time funds transfers between banks with IBAN codes. These transfers are conducted in euros and are commonly used for consumer purchases in SEPA countries.
If you’re a business that is not based within the SEPA area, you wouldn’t use this type of transfer since both the issuing and receiving financial institutions must be located in SEPA countries.
SEPA Instant Credit Transfer
Whereas most transfers between accounts require submitting a transfer request and waiting anywhere from hours to days for it to be settled, SEPA Instant facilitates real-time transfers. Since 5 October 2025, the scheme no longer sets a maximum amount, though each bank can set its own limit.
Using this method, euro-based transactions can be completed by any two account holders in the SEPA area at any time, on any day, and will be processed immediately. Ninety-nine percent of SEPA Instant Credit Transfers are completed within five seconds and can be made using smartphones.
SEPA Direct Debit
Direct Debit is not exclusively for non-EU businesses to interact with accounts within SEPA. SEPA Direct Debit is a reusable notification payment method, which means payment data from it can be internally associated with the customer and reused by the business in authorized capacities.
It’s also a delayed notification payment method, meaning the success or failure of the transaction is only known after the transaction has finished processing, which can take several days.
Bancoli: Local Payouts in Euros
Bancoli gives you named USD account details on every plan, including Free, once your account is verified, and sends local payouts, for example in euros. It streamlines your financial operations and positions your business for global success. The Global Business Account is available on the Enterprise plan only.
Features and Benefits of Bancoli
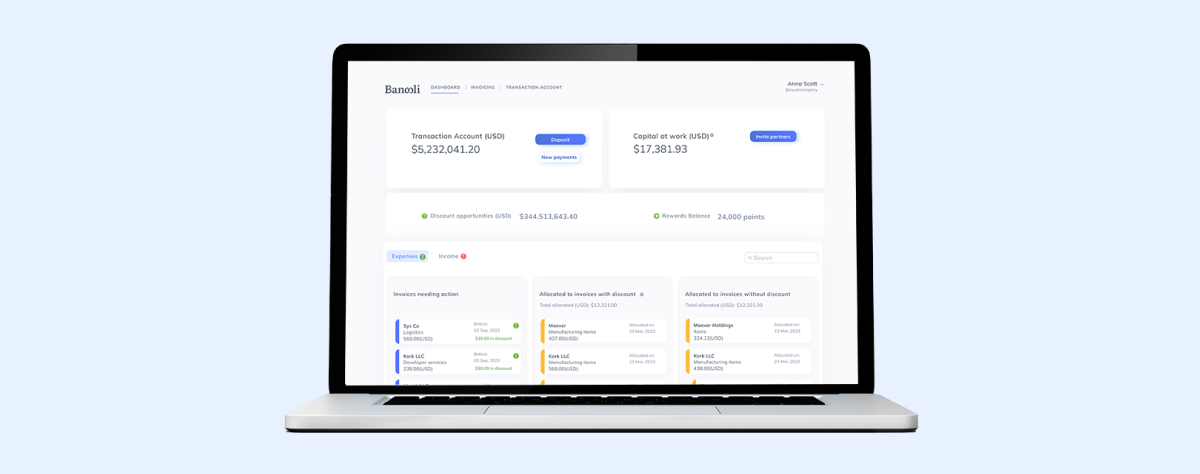
Bancoli is a comprehensive financial tool designed to cater to the multifaceted needs of modern businesses. Below is an in-depth look at its features and benefits:
1. Local Payouts in Euros:
- Bancoli sends local payouts, for example in euros, with free FX in 25+ currencies. This means you can pay European suppliers without SWIFT, which is crucial for businesses engaged in European markets.
2. Free FX in 25+ Currencies:
- Designed for global trade, Bancoli lets you get paid in USD and pay suppliers in currencies such as EUR and GBP with free FX in 25+ currencies. This feature is invaluable for businesses operating in different countries, reducing the impact of fluctuating exchange rates.
3. Tracking and Reporting:
- Bancoli lets you follow payments and invoices in one dashboard, giving businesses a clear view of their financial activities. This supports effective cash flow management and informed financial decisions.
4. Robust Security Measures:
- The account incorporates advanced security protocols, including end-to-end encryption and two-factor authentication (2FA). These measures ensure the safety and confidentiality of financial transactions, which is essential in today’s digital age.
5. Streamlined International Trade:
- The account is an asset for businesses engaged in international trade. It simplifies wire transfers and other cross-border payment methods, making international transactions more straightforward and less time-consuming.
Empowering Global Business Operations
Here is an illustrative example. An e-commerce business sells to US customers and buys inventory from suppliers in Europe. With Bancoli, it gets paid in USD on named USD account details and pays its European suppliers with local payouts in euros, with free FX in 25+ currencies. Invoicing and payments sit in one place, which makes cash flow easier to plan. This is an illustrative example, not a client result.
By providing a versatile, secure, and efficient financial platform, Bancoli empowers businesses to navigate the complexities of global operations, fostering growth and success in the competitive international landscape.
In conclusion
The Single Euro Payments Area (SEPA) has revolutionized the European financial landscape, marking a significant leap in how the global economy handles payments, particularly international payments. SEPA’s streamlined approach to transactions fosters innovation in financial services and enhances the efficiency of operations, playing a crucial role in shaping the future of European and global finance.
The introduction of SEPA has opened up new revenue streams and enabled real-time payments, altering the time perspective in which these transactions are processed quickly and efficiently. As SEPA continues to gain traction, its influence on both the international and European economies is set to grow, offering businesses an undeniable competitive edge.
In this evolving economic climate, leveraging local euro payouts through platforms like Bancoli positions businesses to confidently navigate and thrive in the international financial landscape.
Frequently Asked Questions
1. What types of transactions does SEPA support?
The Single Euro Payments Area supports three primary transaction types: credit transfers (SCT), direct debits (SDD), and card payments. All transactions are processed in Euros and cover various financial activities, such as bill payments, salary deposits, and online purchases.
2. How does SEPA differ from SWIFT?
While both SEPA and SWIFT facilitate cross-border transactions, they serve different purposes. SEPA is focused on cross border transactions, specifically on harmonizing and simplifying Euro payments within Europe. On the other hand, SWIFT is a global messaging network that enables financial institutions to exchange information across borders securely.
3. What security measures are in place for SEPA transactions?
SEPA adheres to strict security guidelines and employs robust measures such as end-to-end encryption, two-factor authentication (2FA), and secure communication protocols to protect sensitive data and prevent fraud.
4. Can non-European businesses benefit from SEPA?
Yes. Non-European businesses can take advantage of SEPA’s streamlined processes and reduced transaction costs by working with payment providers that send local payouts in euros, such as Bancoli.