International transfers remain the backbone of global business payments. When you need to send money across borders securely and efficiently, understanding the process can save you time, money, and stress.
This guide walks you through everything from preparation to confirmation.
What is an International Transfer?
An international transfer is a banking service that electronically transfers money from one bank account to another in a different country.
These transactions enable the making and receiving of international payments without requiring conversion to the local currency before reaching the destination account. The average transfer time ranges from 1 to 5 business days, depending on the banking networks involved.
What Information is Required to Make an International Payment?
Preparation prevents costly delays and rejected transfers. Having the right information ready streamlines the entire process, whether you use your existing bank or a specialized platform.
Essential recipient information:
- Full legal name (exactly as it appears on their bank account)
- Complete mailing address, including postal code and country
- Bank name, city, and country SWIFT/BIC code (8-11 character bank identifier)
- Account number or IBAN (depending on destination country)
- Purpose of payment (required for compliance in many jurisdictions)
Understanding international transfer fees, currency conversion rates, and exchange spreads is crucial for optimizing payment costs. Platforms like Bancoli offer free FX conversion in 25+ currencies, while traditional banks typically charge higher fees.
Other Relevant Information to Make an International Payment
Your business may need additional documentation, particularly for larger transfers or first-time international payments:
- Business registration certificate
- Government-issued ID for authorized signatories
- Proof of business address
- Tax identification numbers
These requirements vary by financial institution and destination country, so verify specific documentation needs during account setup.
Costs in International Payments
Understanding the full cost structure helps you budget accurately and choose the most efficient transfer method:
- Base transfer fee, which varies by provider
- A foreign exchange spread, which varies by currency pair and provider
- Intermediary bank fees on some routes
- Recipient bank receiving fees (varies by institution)
How Does an International Payment Work? Types of International Transfers
Several systems facilitate international payments, with SWIFT and SEPA being the most common.
- SWIFT transfers: The Society for Worldwide Interbank Financial Telecommunication (SWIFT) facilitates money transfers between banks worldwide. Each banking institution has an 8-11 character alphanumeric SWIFT code (also known as a BIC, or Bank Identifier Code) that ensures secure transaction routing.
- SEPA transfers: The Single Euro Payments Area facilitates bank transfers in euros within the eurozone, covering European Union countries as well as several other European countries.
Understanding fees, exchange rates, and processing times is essential since these vary significantly between methods and providers. Always double-check recipient details, as errors lead to delays and additional fees.
What is the Difference Between “Currency” and “Foreign Currency”?
Currency refers to the official legal tender of a country, which is typically represented by coins or paper money issued and regulated by a government or central bank. Foreign currency is any money that isn’t the official legal tender of your country.
For example, if you’re in Mexico, the Mexican peso (MXN) is the local currency, while US dollars (USD) or euros (EUR) are considered foreign currencies.
Step-by-Step International Payment Process
Steps 1-2: Account setup & verification
The most convenient approach uses online banking platforms. Whether through your existing bank’s online portal or specialized B2B payment platforms like Bancoli, digital platforms streamline the verification and transfer process.
Registration process:
- Create your business account using your company email
- Upload required documents (business registration, ID, and address proof)
- Complete verification to access international transfer capabilities
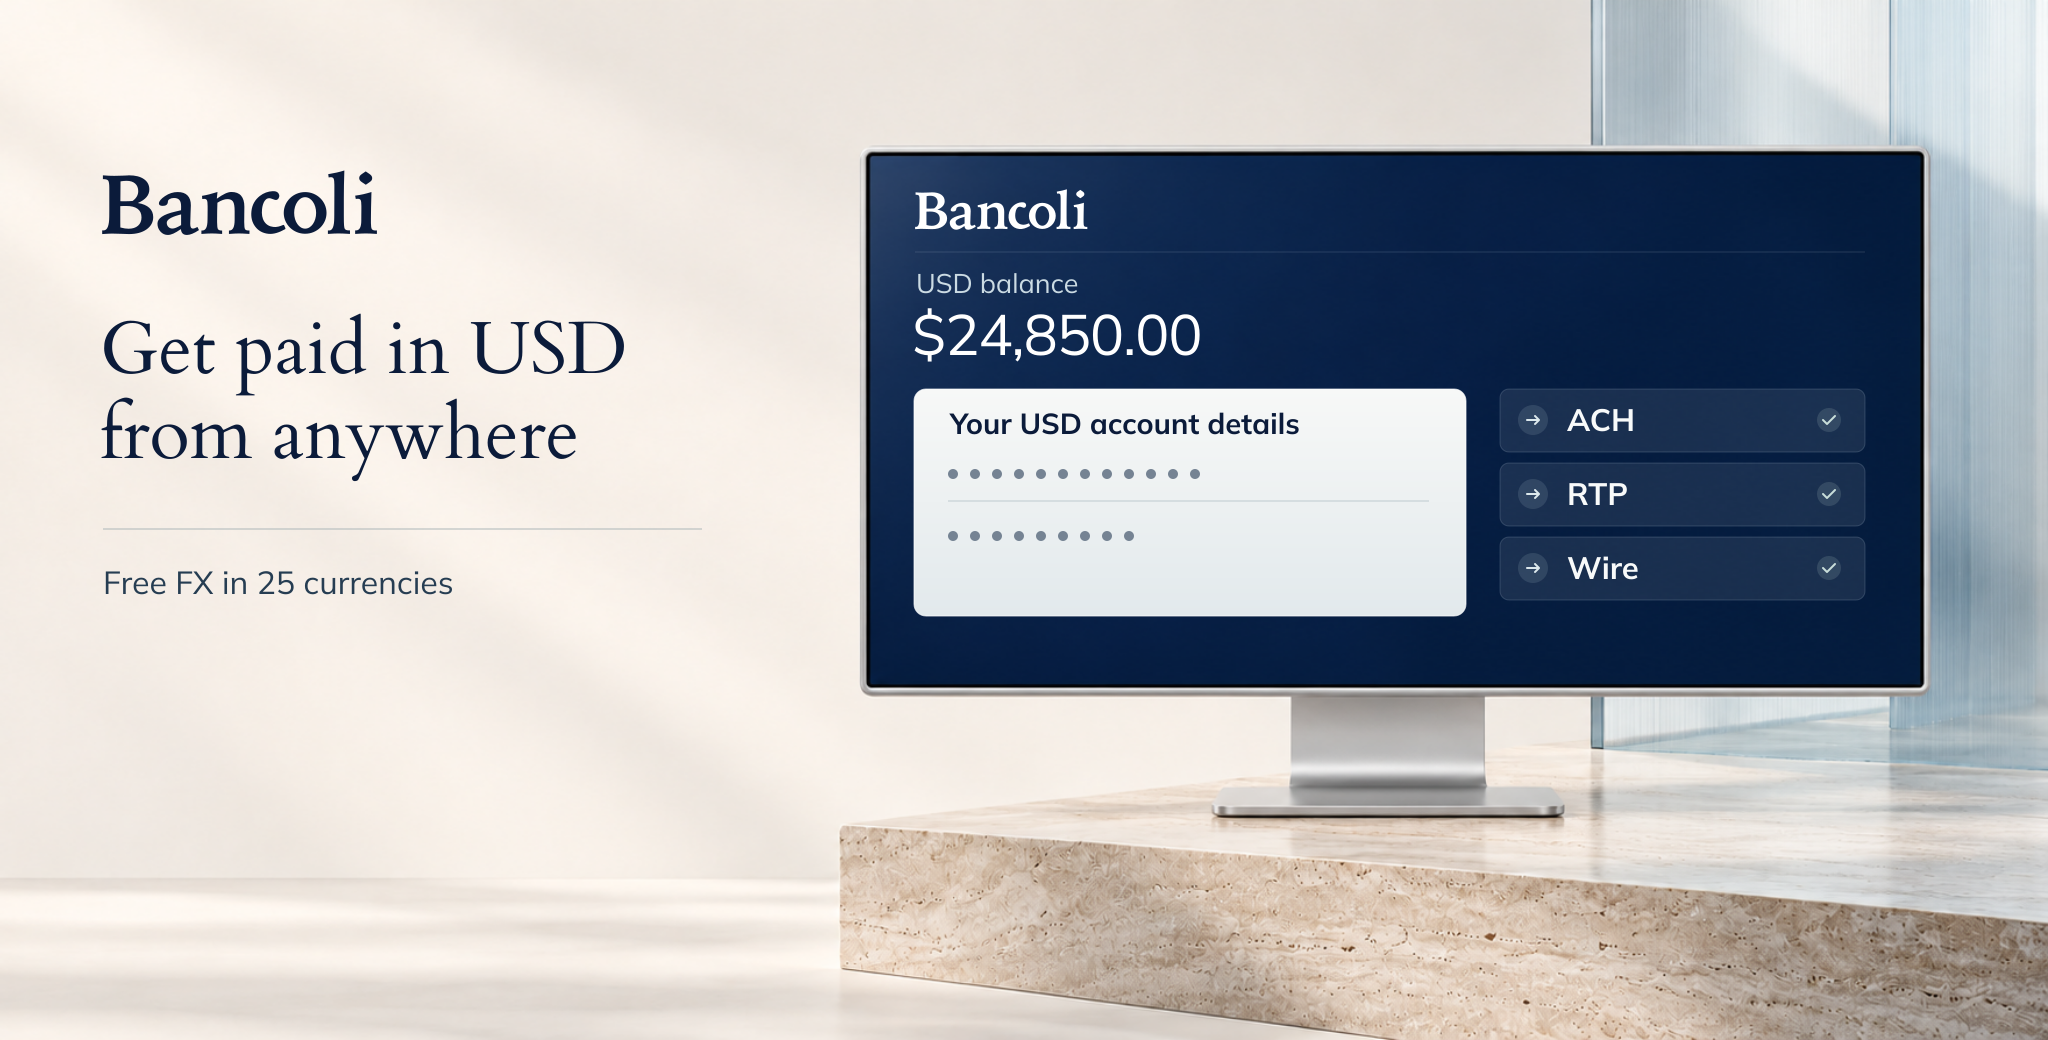
Modern platforms offer additional advantages once verified, including named USD account details. Clients can pay you from a US bank account by ACH, RTP or US domestic wire, or pay in stablecoins, all in one business account.
Step 3: Test transfer strategy
Before sending large amounts, it is recommended to test with $100-200. This reveals:
- Total fees charged to you
- Amount your recipient actually receives
- Any intermediary bank deductions
- Processing time for this specific corridor
This small investment helps prevent expensive surprises on larger transfers.
Step 4: Main transfer execution
With verification complete, initiate your payment:
- Select “International transfer” from your account dashboard
- Enter recipient details (double-check the bank code and account number)
- Review all fees upfront before confirming
- Pro tip: When both parties use Bancoli, transfers between Bancoli accounts are included on every plan.
Critical verification points:
- Recipient name matches the bank account exactly
- SWIFT code corresponds to the correct bank and branch
- Currency selection matches the recipient’s account type
Step 5: Tracking & confirmation
Monitor transfer status through your platform dashboard. Most transfers complete within 1-5 business days, depending on:
- Correspondent banking relationships
- Recipient country regulations
- Currency conversion requirements
Step 6: Recipient verification
Confirm with your recipient:
- Exact amount received in their currency
- Any local bank charges deducted
- Timeline from your send to their receipt
This establishes a baseline for future transfers and ensures that no unexpected deductions are made.
Different Ways to Transfer Money Globally
Understanding transfer types helps optimize your payment strategy and manage costs effectively.
Transfer type definitions:
Payment: Movement associated with an invoice or payment request. These transfers often have additional documentation requirements, but may qualify for better business rates.
Transfer: Direct money movement without invoice requirement, including money withdrawals and movements to external accounts for operational purposes.
Deposit: Incoming funds from external sources where no invoice exists. These are processed as transfers to simplify categorization.
Cost structure breakdown:
Base transfer fees vary by provider and corridor. Some providers offer volume discounts for frequent senders.
FX conversion costs vary by currency pair and provider. Bancoli offers free FX conversion in 25+ currencies.
Intermediary charges: Traditional banks often route payments through correspondent banks, and some of them charge a fee. Modern platforms with direct banking relationships minimize these hidden costs. See Bancoli’s pricing for current fees.
Timeline factors:
- Same-currency transfers: usually the fastest
- Currency conversion required: often takes longer
- Complex routing (multiple intermediaries): can take longer still
- Enhanced due diligence checks: can add extra days
Pro Tips for Success in International Payments
Always test small amounts first. Never send large amounts without testing the corridor. A $100-200 test reveals the true cost structure and timeline. Calculate the percentage loss and apply it to larger amounts for accurate budgeting.
Negotiate timelines with recipients. If account setup takes several days, communicate transparently: “I’m setting up a more efficient payment method that will save us both money on fees. Can we adjust the timeline by one week for a cleaner, faster process?”
Verify details twice. SWIFT code errors are the leading cause of delayed transfers. Use online SWIFT code validators and confirm with recipients before sending.
Track transfers. Modern platforms provide tracking numbers and status updates. Share these with recipients so they know when to expect funds and can follow up with their banks if needed.
Have backup plans ready. If your primary transfer method fails, have alternative options:
- A SWIFT wire through a traditional bank, which is not encouraged because it is slower and costs more
- Money service providers and credit card payments for smaller amounts
- Digital payment platforms (if both parties have access)
Document everything. Keep records of transfer confirmation numbers, exchange rates applied, total fees charged, and recipient confirmation of receipt. This documentation helps with accounting, tax purposes, and troubleshooting future transfers.
When to Use a US Domestic Wire
Best use cases:
- Large business payments ($10,000+)
- Real estate transactions
- Supplier payments requiring formal documentation
- Payments where both parties need a clear audit trail
- Payments that need same-day, final settlement
Consider alternatives when:
- Sending smaller amounts (under $1,000) where percentage fees are high
- Recipients prefer other methods (cards, digital wallets)
- Same-day settlement isn’t critical
Quick decision framework: Use a US domestic wire when security, documentation and same-day settlement matter more than cost. For payments abroad, SWIFT wires are not encouraged. Consider alternatives when convenience and lower fees for smaller amounts take priority.
Conclusion
International payments are part of doing business across borders. With proper preparation and the right route for each payment, they can be secure, traceable and reliable. The key is understanding the process, testing small amounts first, and choosing platforms that are clear about their fees.
Frequently Asked Questions
How long do international payments take?
Timing depends on the route. Same-currency transfers are usually the fastest, currency conversion often takes longer, routing through several intermediary banks can take longer still, and enhanced due diligence checks can add extra days.
What information do I need to send an international payment?
You need the recipient’s full legal name (exactly as it appears on their bank account), complete mailing address including postal code and country, bank name and location, SWIFT/BIC code, account number or IBAN, and the purpose of payment. Always double-check the SWIFT code, as errors are the leading cause of delayed transfers.
How much do international payments cost?
Costs include a base transfer fee, which varies by provider, a foreign exchange spread, which varies by provider, intermediary bank fees on some routes, and recipient bank receiving fees. The total cost varies significantly between providers and currency corridors.
What’s the difference between SWIFT and SEPA transfers?
SWIFT transfers use the Society for Worldwide Interbank Financial Telecommunication network for global money transfers between banks worldwide. SEPA (Single Euro Payments Area) facilitates euro transfers within the eurozone, covering EU countries plus several other European countries.
Should I test with a small amount before sending a large transfer?
Testing with $100-200 before sending large amounts reveals the total fees charged, the amount your recipient actually receives, any intermediary bank deductions, and the processing time for that specific corridor. This small investment prevents expensive surprises on larger transfers.
What documents are required for business verification?
Typically, you will need a business registration certificate, a government-issued ID for authorized signatories, proof of your business address, and your tax identification number. Requirements vary by financial institution and destination country, so verify specific documentation needs during account setup.
What’s the difference between payment, transfer, and deposit types?
Payment refers to the process associated with an invoice or payment request, often accompanied by additional documentation requirements, but potentially offering better business rates. Transfer is a direct money movement that does not require an invoice for operational purposes. A deposit refers to incoming funds from external sources where no invoice exists.
When should I use a US domestic wire instead of other payment methods?
Use a US domestic wire for large business payments ($10,000+), real estate transactions, supplier payments requiring formal documentation, payments needing a clear audit trail, and payments that need same-day, final settlement. For payments abroad, SWIFT wires are not encouraged. Consider alternatives for smaller amounts under $1,000, such as when percentage fees are high, recipients prefer other methods, or when same-day settlement isn’t critical.
How can I track my international transfer?
Ask your provider for the payment confirmation and reference number. Share them with recipients so they know when to expect funds and can follow up with their banks if needed. Most transfers show progress through correspondent banking relationships and regulatory checkpoints.
What happens if I enter wrong recipient details?
SWIFT code errors are the leading cause of delayed transfers. Incorrect details can result in transfers being returned, delayed, or sent to the wrong accounts. Always use online SWIFT code validators and confirm all details with recipients before sending. Keep detailed documentation of all transfer details for troubleshooting purposes.
Why are there intermediary bank fees?
Traditional banks often route payments through correspondent banks, and some of them charge a fee. These intermediary banks facilitate the movement of funds between your bank and the recipient’s bank across different countries and banking networks. Modern platforms with direct banking relationships can minimize these hidden costs.
What’s the difference between currency and foreign currency?
Currency refers to the official legal tender of a country: coins or paper money issued and regulated by a government or central bank. Foreign currency is any money that isn’t the official legal tender of your country. For example, if you’re in Mexico, the Mexican peso is the local currency, while US dollars or euros are considered foreign currencies.
Can international payments be faster?
International payments can be faster when fewer banks sit in the middle. Traditional bank-to-bank transfers typically require 1-5 business days due to correspondent banking networks and regulatory requirements. When both parties use Bancoli, transfers between Bancoli accounts are included on every plan.
What should I do if my transfer is delayed?
Contact your financial institution with your transfer confirmation number and tracking details. Delays often result from enhanced due diligence checks, correspondent banking relationships, or recipient country regulations. Having complete documentation helps resolve issues faster.
How can I minimize international payment costs?
Test small amounts first to understand the true cost structure. Choose platforms with transparent fee structures and competitive exchange rates. For frequent transfers, look for volume discounts. When both parties use Bancoli, transfers between Bancoli accounts are included on every plan. Always compare total costs including hidden intermediary fees, not just advertised rates.