Cross-border finance has evolved from a line-item expense into the nervous system of modern commerce. CFOs entering 2026 now face an unavoidable reality: the “hidden tax” of legacy transfers (FX spreads, settlement delays, reconciliation friction) is bleeding margins in ways spreadsheets can no longer hide.
Meanwhile, the G20 roadmap has reached its final implementation phase. ISO 20022 now mandates richer payment data structures, forcing the market into two camps. On one side sit legacy bank wires with opaque, unpredictable fees. On the other hand, modern multi-rail treasury stacks route funds intelligently based on speed, cost, and corridor.
Consequently, this guide deconstructs the 2026 landscape for global B2B payments. You’ll see how platforms like Bancoli allow forward-thinking finance teams to operate with global treasury precision without adding headcount.
1. The 2026 Reality: Speed, Cost, and Data in Cross-Border Finance
Recently, regulators and fintech leaders converged on three non-negotiable outcomes for B2B payments. Instant liquidity, transparent pricing, and structured data are no longer aspirational. They’re baseline expectations.
Therefore, the winning strategy in 2026 isn’t about “picking a bank.” It’s about rail-agnostic routing: sending each payment via the most efficient network (ACH, local rail, stablecoin, or SWIFT) based on that transaction’s specific constraints. This flexibility has become critical for optimizing modern cross-border payment flows.
In 2026, standardization wins. Routing each payment by corridor helps lower operational costs.
2. Deconstructing the Hidden Cost Stack in Global B2B Payments
Currently, most finance teams track the visible $25 wire fee. However, they routinely miss the operational leakage that accounts for the bulk of costs in cross-border finance. The true “total cost of payment,” prioritized by impact, includes:
- FX Margin (the silent erosion): The spread between the interbank rate and the “retail” rate your provider applies. This often costs 2-4%.
- Settlement latency: The working capital cost of funds trapped in transit for 2-5 days (the “float”).
- Exception handling: The administrative cost of repairing payments due to bad data. Notably, stricter ISO 20022 validation amplifies this.
- Reconciliation labor: The manual hours spent matching vague bank statement descriptions to ERP invoices.
The CFO’s Math
For example, if your effective blended cost is 2% on $10M/year in flow, you’re leaking $200,000/year directly from EBITDA. That’s before accounting for the staff hours spent on payment investigations.
3. The Solution: Multi-Rail Routing for Cross-Border Finance
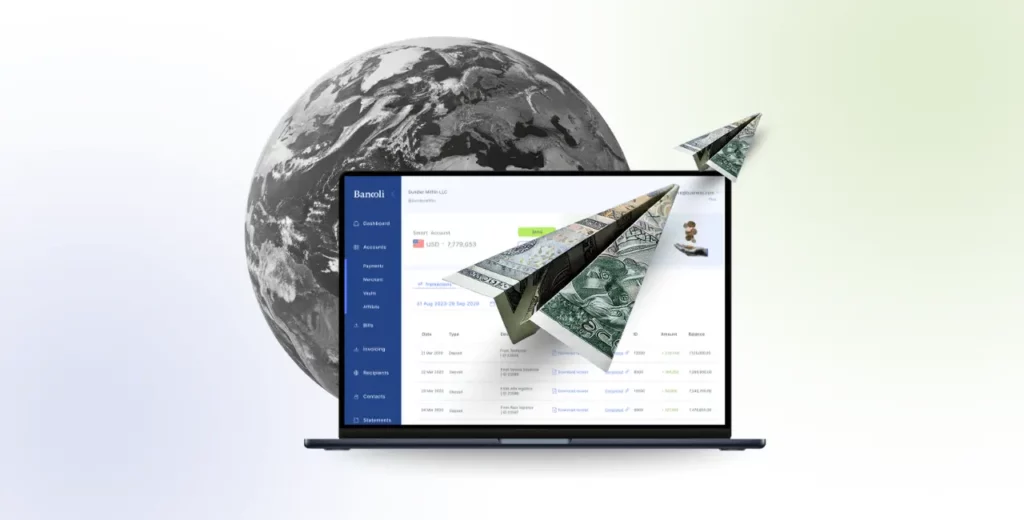
By contrast, a modern treasury stack replaces fragmented banking portals with a single operating layer. Specifically, this approach (central to Bancoli’s Smart USD Wallet) lets businesses get paid in USD and pay globally from a unified interface. This streamlines global B2B payments by design.
The 2026 Multi-Rail Stack
- Local rails (like ACH): Maximum cost efficiency for domestic-like payouts.
- Named USD account details: Get paid by ACH, RTP, US domestic wire and stablecoins into a single account.
- Local payouts: Pay vendors abroad in their local currency, with free FX in 25+ currencies.
- Instant Checkout: ACH debit payments right from the invoice, on paid plans.
- Stablecoin integration: Liquidity movement on blockchain networks where regulatory frameworks permit.
Bancoli Advantage: By integrating these rails, businesses get free FX on local payouts in 25+ currencies.
Multi-rail routing isn’t just about options. It’s about choosing the rail that protects your margin on each payment.
4. Provider Benchmarking: Directional Pricing Signals for Global B2B Payments
Moreover, pricing transparency has become the new baseline. Below is a directional look at how the market structures costs in Q1 2026:
| Provider | FX Margin Context | Transfer Fee Structure | Best For |
|---|---|---|---|
| Traditional Banks | High (2.5% to 4%+) | Wire Fees ($15 to $45) | Legacy relationships & physical branches. |
| Wise Business | Mid-Market + Variable Fee (~0.4% to 0.6%) | Fixed Fee per transfer | Micro-transactions & transparent spot transfers. |
| Revolut Business | Interbank (within allowance) then ~0.4% to 0.6% | Subscription-based allowances | Teams needing spend management cards + FX. |
| Payoneer | Variable Spread (0.5% to 3%) | Withdrawal/Network fees | Marketplaces & freelance gig platforms. |
| Bancoli (Multi-Rail) | Free FX (25+ currencies) | Plans: Free, Plus US$29, Premium US$199 | USD collection and local payouts in one place. |
Note: Comparisons based on publicly available B2B fee structures as of Q1 2026. Always verify specific corridor pricing.
5. Implementation: The 90-Day Treasury Modernization Map
Fortunately, transforming your payment operations doesn’t require a full overhaul. Simply follow this “F-Pattern” execution plan to upgrade your international treasury management:
First: Visibility & Measurement
- Audit: Map your top 5 corridors by volume and value.
- Access: Open a Smart USD Wallet to establish a USD operational hub.
- Identify: Flag recurring payments losing margin to high FX spreads.
Second: Routing Optimization
- Switch: Route recurring payouts to local rails with Bancoli local payouts, which include free FX in 25+ currencies.
- Consolidate: Direct international receivables to your named USD account details to centralize liquidity.
Third: Scale & Policy
- Policy: Set internal approval limits based on transaction value.
- Integration: Ensure remittance data flows cleanly into your accounting layer.
- Review: Measure the reduction in “total cost of payment” and settlement time.
Conclusion
Cross-border finance in 2026 goes beyond choosing a single provider. Now, it’s about deploying an intelligent routing system that optimizes every transaction by corridor.
Companies adopting multi-rail treasury platforms are cutting per-transaction costs and reconciliation work. Ultimately, the question isn’t whether to modernize global B2B payments, but how quickly you can deploy a system that turns payment operations from a cost center into a competitive advantage.
Frequently Asked Questions About Global B2B Payments
How does the Smart USD Wallet differ from a traditional multicurrency account?
Instead of holding balances in many currencies, the Smart USD Wallet is built around USD. You get paid into named USD account details by ACH, RTP, US domestic wire and stablecoins, and you send local payouts with free FX in 25+ currencies. Bancoli does not hold non-USD balances.
What is the impact of ISO 20022 on cross-border finance?
ISO 20022 mandates richer data structures for payments. Consequently, businesses experience fewer failed payments due to missing information. Moreover, invoice details now travel with the funds, enabling automated reconciliation.
Can I use stablecoins for B2B supplier payments?
Yes. Modern treasury stacks let you settle in stablecoins (like USDC). Settlement time depends on the network. This is particularly useful for corridors where traditional banking rails are slow or expensive.
How does free FX work in global B2B payments?
Bancoli local payouts include free FX in 25+ currencies, on every plan. Plan prices (Free, Plus US$29 and Premium US$199) are on the Bancoli pricing page.
Is my liquidity safe in a fintech platform?
Banking services are provided by regulated providers, including Bancoli’s affiliated chartered bank. You control your funds. Bancoli does not own or control them. Smart USD is not a deposit and is not FDIC-insured.