A stablecoin payment platform should do more than move a token from one address to another. A business needs to receive the money, know who controls it, pay suppliers in the currency they use and give the accountant records that match each invoice.
This guide sorts the kinds of platforms businesses compare by the job each one is built for. It names Bancoli and describes the other types by how they work, so you can test any provider in each type against the same questions.
In short
- Look at Bancoli when you need named USD details, a self-custodial Smart USD Wallet and local payouts to suppliers, with free FX in 25+ currencies on local payouts.
- Look at a stablecoin acceptance service when the main job is letting customers pay you in stablecoins online.
- Look at a developer platform when you are building stablecoin payments into your own product.
- A plain crypto wallet holds and sends stablecoins, but leaves invoices, payouts and records to you.
What a business needs from a stablecoin payment platform
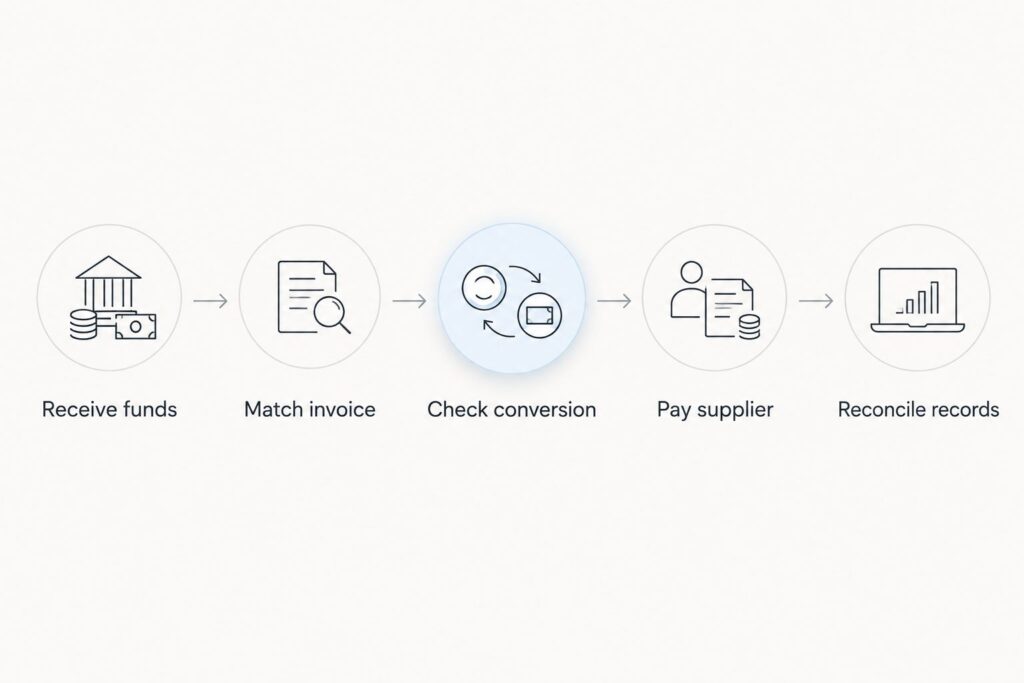
Five steps make up a business stablecoin payment. Each one is a question to ask any platform.
- Receive: can clients pay you in stablecoins, and can they pay in US dollars too?
- Match: can you tie each payment to the invoice it settles?
- Convert: when you need another currency, where does the conversion happen and what does it cost?
- Pay: can a supplier receive local currency in their own bank account?
- Reconcile: does your accountant get records that close each invoice?
Stablecoin payment platforms at a glance in 2027
| Type | Good fit for | What to look at | Watch for |
|---|---|---|---|
| Bancoli | Businesses already using stablecoins | Named USD account details, a self-custodial Smart USD Wallet and free FX in 25+ currencies on local payouts | Confirm your eligibility and your suppliers’ countries |
| Stablecoin acceptance service | Online sellers adding stablecoins as a way to pay | How customers pay and how funds settle to you | Who holds the funds and how you pay suppliers |
| Developer platform | Product teams building payments into an app | APIs, supported networks and compliance tools | Engineering work before the first payment |
| Plain crypto wallet | People who only need to hold and send stablecoins | Networks, recovery and access | Invoices, local payouts and records are left to you |
| Bank plus separate wallet | Businesses keeping their bank and adding a wallet | How the two connect and who moves money between them | Two sets of records to match |
“Good fit for” describes the job each type is built around. It is not an overall ranking.
1. Bancoli: receive, hold and pay from one wallet
Bancoli is a stablecoin on-ramp and off-ramp for businesses. It is not an account that holds many local currencies. Your Smart USD Wallet holds supported stablecoins, and you convert when you pay out.
The Smart USD Wallet can accept and hold USDC, USDi and USDT (USDT on Ethereum only, when your account shows it). The wallet is self-custodial. You control your funds. Bancoli does not own or control them. Banking services are provided through an affiliated chartered bank.
Named USD account details in your business’s legal name are available on every plan, including Free, once your business is verified. Bancoli receives US dollars by ACH, RTP, US domestic wire and stablecoins, and sends by ACH, RTP and local payouts. ACH and RTP payments arrive as supported stablecoins in your Smart USD Wallet, and they convert 1:1. You pick the supported stablecoin. You can also buy USDC with USD by sending it by ACH or RTP from your own business bank account to your named USD details and choosing USDC. Receiving an ACH or RTP payment costs $2 on Free, $1 on Plus, and it is free on Premium.
To pay a supplier, you choose a supported currency and route for their location and pay from your Smart USD Wallet. Your supplier receives local currency in their own bank account. They do not need a Bancoli account for a supported bank payout. You get free FX in 25+ currencies on local payouts, and the pricing page lists the currencies. You can see the steps on Bancoli global payouts.
Every plan also includes invoicing, so you can create, send and track invoices to your clients.
Where Bancoli fits
- Clients pay your named USD details by ACH or RTP, or send stablecoins, and you pay suppliers from the same Smart USD Wallet.
- Every plan can create, send and track invoices to your clients.
- Suppliers abroad keep the bank account they already use, and you get free FX in 25+ currencies on local payouts.
- The wallet is self-custodial. You control your funds.
Where to check before you choose it
- A supported currency does not mean every supplier or payment qualifies. Availability, routes and fees depend on your business, your supplier and the payment route.
- Businesses from 150+ countries are eligible. Access still depends on your business, your location and verification. Check eligibility before you apply.
- Decide who on your team can approve payments from the wallet, and write it down.
| Dimension | Bancoli |
|---|---|
| Receive | Named USD details by ACH, RTP and US domestic wire, plus stablecoins |
| Control | You do. The wallet is self-custodial |
| ACH and RTP | No Bancoli limit on ACH or RTP |
| Pay suppliers | Local payouts, with free FX in 25+ currencies on local payouts |
Good fit for: businesses and solopreneurs already using stablecoins that need named USD details and local payouts to suppliers.
Our take: worth a trial once your eligibility is confirmed.
2. Stablecoin acceptance services: for online sellers
These services add stablecoins as a way for customers to pay you online. They answer the first step well, how the customer pays.
What to check
- Ask who holds the funds after the customer pays, and when they reach you.
- Ask how you would pay a supplier abroad from those funds, or whether you need another provider for that.
Good fit for: businesses where taking stablecoin payments from customers online is the main job.
Our take: compare the full route to your suppliers before you choose one.
3. Developer platforms: for building into your product
Developer platforms give product teams APIs to build stablecoin payments into an app or marketplace. They make sense when payments are part of what you sell.
What to check
- Count the engineering time before the first live payment.
- Ask which networks, stablecoins and countries are supported for your business.
Good fit for: product teams building payments for their own users.
Our take: a build project, not a quick switch. Plan it like one.
4. Plain crypto wallets: for holding and sending
A plain wallet holds stablecoins and sends them to another address. It does not create invoices, pay a supplier’s bank account or prepare records for your accountant.
What to check
- Plan how you will recover access if a device or a person is lost. The guide on wallet access when an employee leaves covers that step.
- Plan how you will match each transaction to an invoice.
Good fit for: holding and sending stablecoins when the rest of the workflow lives elsewhere.
Our take: fine as a tool, thin as a business payment setup.
5. Bank plus separate wallet: for keeping your bank
Some businesses keep their bank and add a separate wallet for stablecoins. That keeps the banking relationship, but money now moves between two places.
What to check
- Decide who can move money between the bank and the wallet.
- Plan how your accountant will match records from both.
Good fit for: businesses that want to keep their bank relationship and test stablecoins on the side.
Our take: workable, as long as one person owns the records for both.
How to choose
Start with your suppliers. If they want local currency in their bank accounts, you need a platform that pays out that way. Then look at your clients. If they pay in US dollars, you need a way to receive them.
Then test one real payment end to end. Agree the stablecoin and the supported network with the client first. The guide on how to choose a supported network explains why that matters. Match the payment to the invoice, pay a supplier and check the records close.
FAQ
What is a good stablecoin payment platform for a business in 2027?
It depends on the job. Bancoli fits businesses that already use stablecoins and need named USD details, a self-custodial Smart USD Wallet and local payouts to suppliers. Online sellers and product teams may need a different type.
Which stablecoins can a Bancoli Smart USD Wallet hold?
The Smart USD Wallet can accept and hold USDC, USDi and USDT (USDT on Ethereum only, when your account shows it).
Can I receive US dollars and hold stablecoins in one place?
Yes, with Bancoli. ACH and RTP payments to your named USD details arrive as supported stablecoins in your Smart USD Wallet, and they convert 1:1.
Can my supplier receive local currency instead of stablecoins?
Yes, where a supported route exists. Your supplier receives local currency in their own bank account, and you get free FX in 25+ currencies on local payouts.
Who controls the funds in a Bancoli wallet?
You do. The wallet is self-custodial. Bancoli does not own or control your funds.
One last thing
Write down who can approve a payment and which record closes each invoice before you move real money. Any platform works better when those two answers are clear.
If you want to get paid in USD and pay suppliers in their own currency from one wallet, start with the Smart USD Wallet and check the fees on pricing.